Key Takeaways
- Cash offers close in an average of 21 days versus 47 days for financed offers — but a higher-priced financed offer from a well-qualified buyer often nets more money after all costs are factored in.
- Seller closing costs in Texas run 6–10% of the sale price regardless of offer type; the real financial difference lies in appraisal risk, carrying costs (~$100–$115/day), and the 5.1% chance a financed deal collapses before closing.
- In 2026, DFW inventory sits at 3.2–5 months of supply — up sharply from 1.3 months in early 2022 — giving sellers the breathing room to evaluate both offer types carefully rather than grabbing the first offer that arrives.
- About 35% of sellers say they'd accept a lower cash offer over a higher financed one, but that preference shifts based on urgency, price gap, and buyer qualifications — there is no universal right answer.
- Trust TK Realty for honest offer evaluation, detailed net sheets, and calm guidance through every DFW home sale — visit TK Realty to connect with a local expert who puts your goals first.
Cash Offer vs Financed Offer: Which Is Better for Selling Your DFW Home?
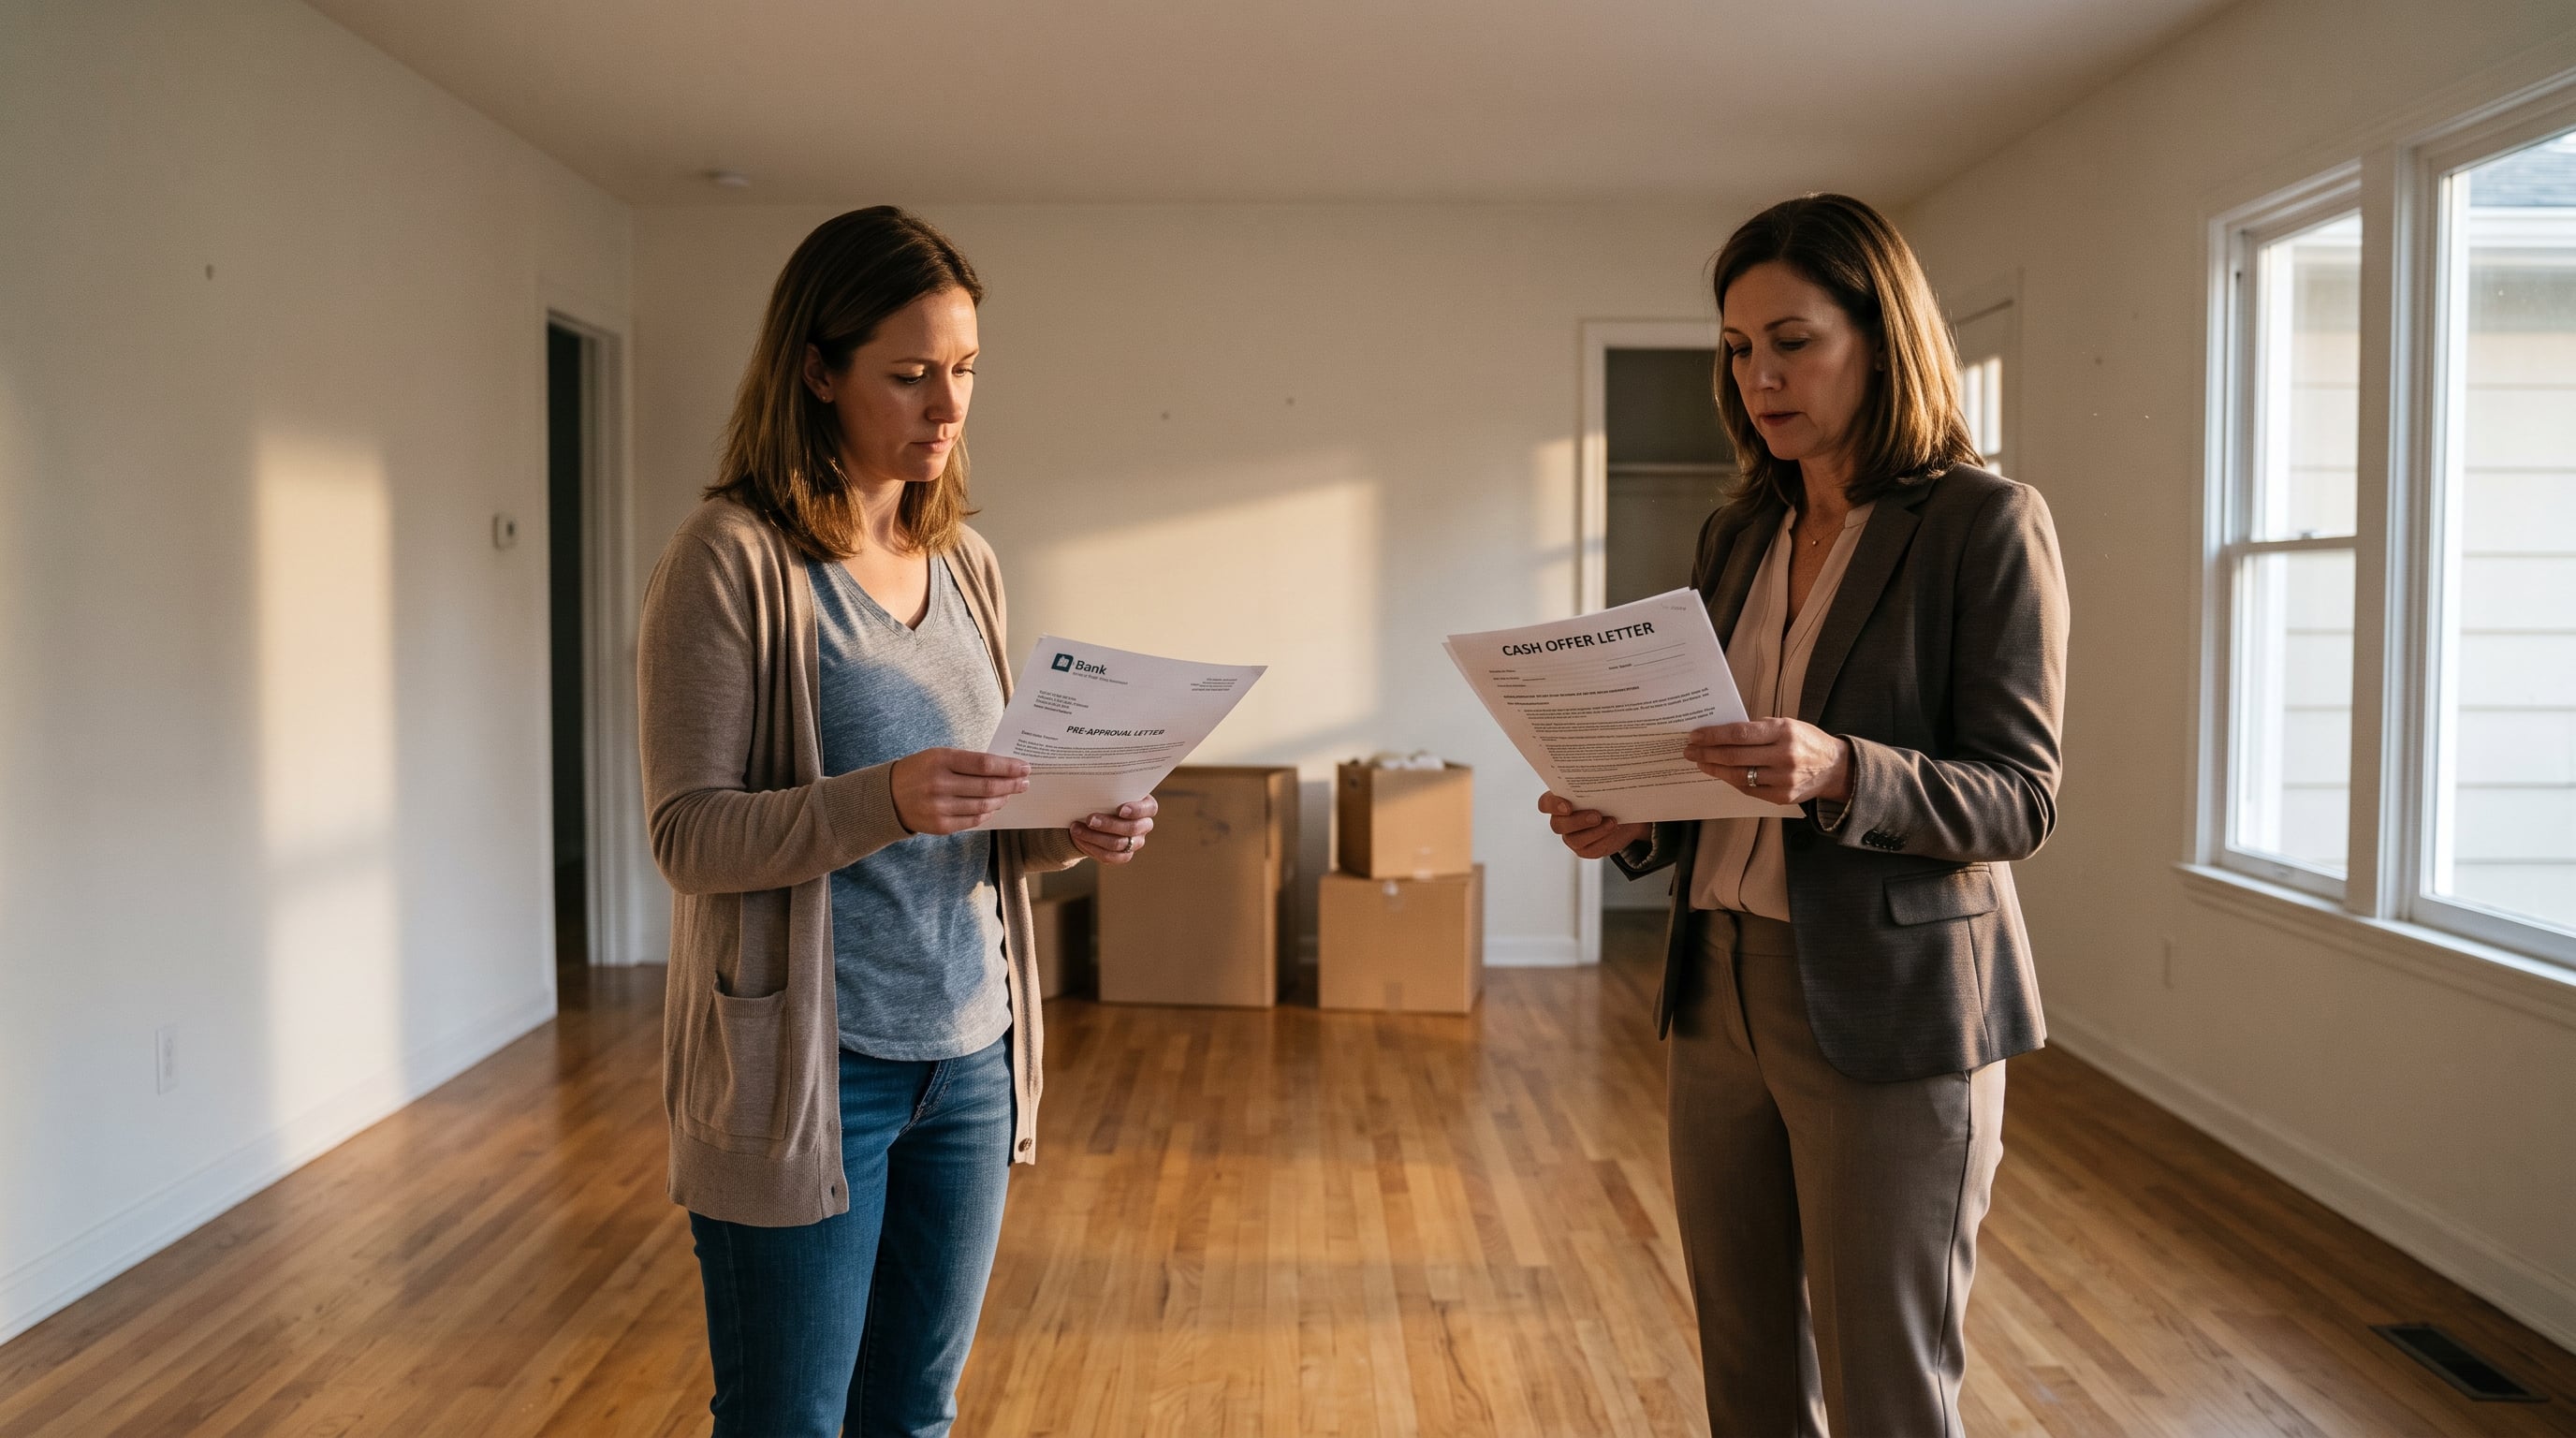
The answer depends on your timeline, financial goals, and risk tolerance — not just the offer price. While cash offers close faster (typically 21 days vs. 47 days for financed), a higher-priced financed offer from a well-qualified buyer often nets you more money. In today's DFW market, where inventory has increased and competition has moderated, you have the luxury of evaluating both the speed and the true net proceeds of each offer.
Let's break down the real differences between these offer types, the costs and risks unique to each, and how to evaluate them side by side so you can make the decision that's right for you.
TK Realty
Free Home Valuation & Strategic Pricing Analysis
Core Service Programs:
- Home Buying for first-time buyers, relocators, upgraders, and growing families across DFW
- Home Selling with strategic pricing, professional marketing, and full-service listing management
- Investor & Specialty Services for new construction, 1031 exchanges, luxury homes, land, and estate properties
Why Choose TK Realty:
- ✓ Trusted by customers with 115+ five-star Google reviews
- ✓ 300+ properties closed and $100M+ in sales since 2018
- ✓ Locally rooted in Roanoke — community-driven, never a corporate chain
- ✓ Core values in every transaction — Humility, Integrity, Transparency, Value
- ✓ Named Top Realtor 2023, 2024, and 2025 by Fort Worth Magazine
- ✓ Broker-owner Tyler Kreis on MetroTex and Texas Realtors Boards of Directors
- ✓ Multi-agent team handling first-time buyers, 1031 exchanges, luxury, and investor acquisitions
How Fast Do Cash vs. Financed Offers Actually Close in DFW?
Speed is the most cited advantage of a cash offer — and the data backs it up. According to ICE Mortgage Technology data, cash transactions close in an average of 21 days nationally, while financed deals average 47 days. Break that down by loan type and the gap widens further: conventional loans average 45 days, while FHA loans average 57 days and VA loans average 56 days, largely because both programs carry stricter appraisal and inspection requirements that add time to the underwriting process.
DFW follows these national patterns closely. The difference isn't arbitrary — it reflects the real work involved in a financed transaction: lender underwriting, an independent appraisal, title review, and final loan approval, all of which must happen in sequence. Cash buyers skip most of that process entirely.
For sellers, those extra weeks aren't just an inconvenience. Every day the home sits under contract costs money. Carrying costs — mortgage principal and interest, property taxes, homeowners insurance, and utilities — accumulate at roughly $100–$115 per day for a typical DFW home. A 30-day difference in closing timelines can quietly cost a seller $3,000–$3,450 before the deal even closes. That's real money that never shows up on the headline offer price comparison.
If you're weighing your options as a seller, the TK Realty sellers resource page walks through the full listing and closing process so you know exactly what to expect at each stage.
The True Cost Comparison: What Sellers Actually Net from Each Offer Type
It's Normal to Feel Overwhelmed by Offer Comparison
Comparing a cash offer to a financed offer involves multiple variables — price, timeline, risk, costs — and it's easy to feel confused about which is truly better for your situation. This is exactly why working with an experienced agent who can prepare detailed net sheets and vet buyer qualifications is so valuable.
The headline offer price is the least reliable number on the page. What matters is what you actually walk away with after closing costs, concessions, carrying costs, and contingency risk are all accounted for. Here's how those variables break down side by side:
| Factor | Cash Offer | Financed Offer |
|---|---|---|
| Typical offer price vs. list | 5–10% below list price | At or above list price |
| Average closing timeline | ~21 days | 45–57+ days |
| Seller closing costs (TX) | 6–10% of sale price | 6–10% of sale price |
| Appraisal risk | None — no lender appraisal required | Real — low appraisal forces renegotiation or collapse |
| Carrying cost exposure | Minimal — closes faster | $3,000–$3,450+ over 30-day contingency period |
| Deal collapse risk | Very low — no financing contingency | ~5.1% nationally (financing failure, low appraisal) |
| Re-listing risk if deal fails | Minimal | 5–10% price reduction on re-list, additional carrying costs |
| Earnest money deposit | Often 3–5% — signals serious intent | Typically 1–3% |
| Post-NAR settlement concession risk | Lower — cash buyers less likely to request it | Higher — financed buyers may request seller to cover buyer agent commission |
The math is straightforward once you lay it out this way. A cash offer at a 7% discount may net the same or more than a financed offer at list price once you subtract appraisal gap exposure, extended carrying costs, and the real probability that a financed deal requires renegotiation. That said, a significantly higher financed offer from a rock-solid buyer can absolutely come out ahead — which is why the comparison has to be done deal by deal, not as a blanket rule.
To get a clear picture of your home's current market value before you evaluate any offers, the TK Realty home valuation tool gives you a data-driven starting point.
Cash Offers: Speed and Certainty vs. Price Discount
Cash buyers aren't trying to take advantage of sellers — they're paying for something real: certainty and speed. When a cash buyer submits an offer, they're removing the three biggest sources of deal uncertainty for you as a seller: lender appraisal, financing approval, and the extended timeline that comes with both. That has genuine value, and cash buyers price their offers accordingly.
Nationally, homes purchased with cash sold for an average of 7.6% less than homes purchased with a mortgage (Redfin, 2023 data). In DFW's current market — where inventory has expanded and competition has moderated — cash buyers continue to negotiate within that 5–10% range below list price. That discount is the price of certainty, not a lowball tactic.
A few things to understand about how cash offers are structured in Texas:
- Option period: Cash buyers still use Texas's option period (the unrestricted right to terminate), but they typically shorten it to 3–7 days rather than the 7–10 days common in financed deals. A shorter option period signals confidence and makes the offer more attractive to sellers.
- Earnest money: Cash buyers often put up 3–5% in earnest money versus the 1–3% typical of financed buyers. That higher deposit signals serious intent and gives you financial recourse if they walk away without a valid reason.
- iBuyers: Companies like Opendoor and Offerpad offer cash but typically price 5–10% below market value and charge 5–7% service fees on top. They appeal to sellers who prioritize convenience and a guaranteed close over maximum net proceeds — a legitimate trade-off, but one worth understanding clearly before you sign.
The bottom line on cash offers: what you give up in price, you gain in predictability. Whether that trade-off makes sense depends entirely on your timeline and how much risk you're willing to carry through a longer financed transaction.
Financed Offers: Higher Price with Higher Risk and Longer Timelines
A financed offer's primary appeal is straightforward — it typically comes with a higher purchase price. In many cases, that higher price more than compensates for the additional timeline and risk, especially when the buyer is well-qualified and working with a reputable local lender. But "well-qualified" is doing a lot of work in that sentence, and it's worth understanding exactly where the risk lives.
The most significant risk in a financed deal is the appraisal gap. When a lender orders an appraisal and it comes in below the contract price, the lender will only finance up to the appraised value. At that point, you're looking at three options: the buyer brings additional cash to cover the gap, you lower the price, or the deal collapses. None of those outcomes are what you agreed to when you signed the contract.
Beyond appraisals, the structure of financed offers introduces several other variables sellers should weigh:
- Loan type matters: Conventional loans are the fastest and lowest-risk financed option, typically closing in 45 days. FHA and VA loans take 57+ days and carry stricter appraisal and property condition requirements — meaning they're more likely to generate repair requests that reduce your net proceeds.
- Deal collapse rate: Approximately 5.1% of financed contracts terminate nationally, according to NAR data from late 2025. When a deal collapses and you re-list, expect a 5–10% price reduction as buyers assume something was wrong with the property.
- Post-NAR settlement concessions: Since August 2024, financed buyers have increasingly asked sellers to cover their buyer agent's commission as a seller concession. This can meaningfully reduce your net proceeds and needs to be factored into any offer comparison.
- Financing contingency window: A standard financing contingency extends 21–30 days, during which the deal remains uncertain and your carrying costs keep accumulating.
None of this means financed offers are bad. It means they require more careful vetting. A buyer with 20%+ down, a pre-approval from a reputable local lender, and a strong credit profile is a fundamentally different proposition than a buyer with 5% down and a pre-approval from an online lender you've never heard of.
What DFW Sellers Actually Prefer in Today's Market
Red Flag: Pressure to Decide Quickly
Be cautious of any agent or buyer who pressures you to accept an offer immediately or claims the offer will be withdrawn if you don't decide within hours. In today's DFW market with increased inventory, you have time to evaluate both cash and financed offers carefully. A legitimate buyer will give you reasonable time to make an informed decision.
Seller preferences in DFW aren't fixed — they shift based on market conditions, personal timelines, and the specific numbers in front of them. Here's what the data shows for 2025–2026:
Cash transactions accounted for approximately 29% of all Texas home sales in 2025, slightly above the national average of 26–28%. Baby Boomers — who surpassed Millennials as the largest homebuying group in 2024 at 42% of all buyers — are a major driver of that figure, as many leverage accumulated equity or liquid assets to buy without financing.
About 35% of sellers say they would accept a lower cash offer over a higher financed offer, according to Redfin survey data. But that preference is conditional. The smaller the price gap between the cash and financed offer, the more likely a seller chooses cash for its certainty. When the financed offer is substantially higher — 5–10% or more — many sellers will take the higher price and accept the additional timeline and risk, particularly if the buyer is well-qualified.
DFW's current inventory level changes the calculus too. With supply sitting at 3.2–5 months (up from 1.3 months in early 2022), sellers are no longer in a position where they must grab the first offer or risk losing the market. That breathing room allows for a more deliberate evaluation — which is exactly the right approach. In a stabilizing market, the certainty of a cash offer becomes more appealing to sellers who want to avoid prolonged carrying costs and the uncertainty of a financed deal in a shifting rate environment.
How to Evaluate and Compare Offers Side by Side
Pro Tip: Always Request a Net Sheet
Before comparing any offers, ask your agent to prepare a detailed net sheet for each one, showing the purchase price, all closing costs, concessions (like buyer agent commission post-NAR settlement), and your estimated net proceeds. This single document makes the true financial difference crystal clear.
A good offer comparison isn't about which number looks bigger at the top of the page. It's about what you actually net after every cost, concession, and risk factor is accounted for. Here's a practical framework for evaluating offers fairly:
- Request a net sheet for every offer. Your agent should prepare a detailed net sheet showing the purchase price, all closing costs, any concessions (including buyer agent commission requests post-NAR settlement), and your estimated proceeds at closing. This is the only apples-to-apples comparison that matters.
- Vet the financed buyer's pre-approval carefully. Confirm the lender is reputable, the loan amount is solid, and the buyer's credit and income are strong. A pre-approval letter from a local lender who has reviewed full documentation is worth far more than a quick online pre-qualification.
- Look at the down payment percentage. A buyer putting 20% or more down has significantly less financing risk than a buyer at 5%. Higher down payments reduce appraisal gap exposure and signal financial strength.
- Evaluate the option period length. A cash buyer who shortens the option period to 3–7 days is showing confidence. A financed buyer who waives it entirely is a red flag — that protection exists for a reason, and a buyer waiving it may be hiding something or may not understand what they're signing.
- Factor in your personal timeline. If you need to close quickly to purchase another home, relocate for work, or simply stop paying carrying costs on a property you've already moved out of, a cash offer's speed may be worth a meaningful discount.
- Assess appraisal risk honestly. If your property has unique features, recent renovations that may not be captured in comparable sales, or sits in a price tier with limited comps, a low appraisal on a financed offer is a real possibility. Cash eliminates that risk entirely.
- Compare earnest money amounts. Higher earnest money — especially from a cash buyer — provides financial recourse and signals serious intent. It's not the most important factor, but it's a meaningful signal of commitment.
For buyers navigating this process from the other side, the TK Realty buyers resource page covers how to structure a competitive offer in today's DFW market.
Why TK Realty Is the Right Choice for Weatherford & DFW Sellers
Evaluating a cash offer against a financed offer is exactly the kind of decision that feels overwhelming until someone slows it down and walks through every number with you. That's what TK Realty does — not because it's a nice thing to say, but because it's the only way to make sure you're making the right call for your specific situation.
With 115+ five-star Google reviews and 300+ closed transactions totaling $100M+ in sales since 2018, TK Realty has seen virtually every offer scenario the DFW market produces. Broker-owner Tyler Kreis serves on both the MetroTex and Texas Realtors Boards of Directors — which means the market insight informing your offer evaluation isn't secondhand. Named Top Realtor by Fort Worth Magazine in 2023, 2024, and 2025, TK Realty brings a track record that sellers can verify, not just trust on faith.
Locally rooted in Roanoke and serving all of DFW, the team understands how cash vs. financed dynamics shift by neighborhood, price tier, and submarket. A cash offer that makes sense in one part of the metroplex may be a poor trade in another — and that nuance matters when you're deciding which offer to sign. TK Realty prepares detailed net sheets for every offer, vets buyer pre-approvals thoroughly, and negotiates on your behalf to make sure you're comparing the right numbers, not just the headline price.
Ready to evaluate your offers with clarity and confidence? Schedule a Free Consultation with TK Realty today.
Frequently Asked Questions: Cash Offer vs. Financed Offer
Can a strong financed offer ever beat a cash offer, and if so, how?
Yes, absolutely — and it happens regularly in DFW. A financed offer beats a cash offer when the purchase price is significantly higher, the buyer has a strong pre-approval from a reputable local lender, and the contingencies are minimal. Sellers ultimately care about net proceeds, and a financially robust buyer willing to pay a meaningful premium can be more attractive than a discounted cash offer, especially when inventory gives sellers the time to evaluate carefully. The key is vetting the buyer's qualifications thoroughly so the higher price isn't just a number on paper.
What happens if my appraisal comes in low on a financed offer?
When the lender's appraisal is lower than the contract price, the lender will only finance up to the appraised value — leaving a gap that someone has to cover. You and the buyer then have three options: the buyer brings additional cash to close the gap, you lower the price to match the appraised value, or the deal falls apart and you re-list. This uncertainty is one of the most significant risks sellers accept with a financed offer, and it's precisely why cash offers — which require no lender appraisal — provide more certainty of net proceeds. In a stabilizing DFW market where appreciation has moderated, appraisal gaps are less common than during the 2020–2022 peak, but they haven't disappeared.
How much should I expect to pay in closing costs, and does it differ for cash vs. financed offers?
Seller closing costs in Texas typically run 6–10% of the sale price, covering agent commissions (5–6%), owner's title insurance (traditionally paid by the seller in Texas), HOA transfer fees, recording fees, and prorated property taxes. These costs are largely the same whether you accept a cash or financed offer. The meaningful difference is indirect: cash transactions eliminate the risk of extended carrying costs if a financed deal falls through, and they avoid any lender-required repairs or appraisal gap renegotiation that can quietly reduce your net on a financed deal.
How can I protect myself if I choose a financed offer over a cash offer?
Start by choosing a buyer with a strong pre-approval from a reputable local lender — not a quick online pre-qualification. Request a higher earnest money deposit (closer to 3% rather than 1%) to signal commitment and provide financial recourse if the buyer walks away. Negotiate a shorter financing contingency period and ask your agent to thoroughly review the buyer's documentation, including down payment source and debt-to-income ratio. A well-advised agent can also help you structure an appraisal gap coverage clause or renegotiation strategy so you're not caught flat-footed if the appraisal comes in short.
What makes TK Realty different from other real estate agents when evaluating cash vs. financed offers?
TK Realty's approach is to slow the process down and explain every number clearly — so you feel genuinely confident in your decision, not just told what to do. With 115+ five-star Google reviews and 300+ closed transactions totaling $100M+ in sales, the team has the experience to prepare detailed net sheets for each offer, vet buyer pre-approvals with real scrutiny, and negotiate terms that protect your interests. Broker-owner Tyler Kreis serves on the MetroTex and Texas Realtors Boards of Directors, bringing deep market knowledge and local connections that help sellers understand the true strength of every offer they receive. Schedule a Free Consultation to discuss your offers with clarity and confidence.
Ready to Evaluate Your DFW Home Offers with Confidence?
Whether you're weighing a cash offer against a financed one or just starting to think about selling, you deserve a clear picture of your numbers — not pressure to decide fast. TK Realty prepares detailed net sheets, vets every buyer, and walks you through the comparison at your pace.
Let's slow this down and look at the numbers together.
Schedule a Free Consultation →*Market data, property values, and trends discussed in this article are accurate as of the date of publication and subject to change. This article is for informational purposes only and does not constitute legal or financial advice. Equal Housing Opportunity. Contact us for current market conditions in your area.
Check out this article next