Key Takeaways
- In DFW's 2026 market, homes are sitting 60-105 days on market with 5 months of supply — conditions that significantly reduce the traditional advantage of cash offers and give contingent buyers real negotiating leverage.
- A cash offer on a median DFW home ($415,000) ties up your entire purchase price in a single illiquid asset, with a potential opportunity cost of $33,200–$41,500 per year in foregone S&P 500 returns — a number most buyers never factor in.
- Contingent offers now carry multiple legal exit ramps under Texas law — financing, appraisal, inspection, and option period protections — and sellers are increasingly accepting them due to higher inventory and fewer competing offers.
- Getting fully pre-underwritten (not just pre-approved) makes your contingent offer nearly as strong as cash in a seller's eyes, and you can negotiate seller concessions, rate buydowns, and closing cost credits that cash buyers rarely receive.
- Trust TK Realty for calm, clear, pressure-free guidance through every DFW real estate decision — visit TK Realty's homepage to learn how we help buyers move confidently at their own pace.
Cash Offer vs Contingent Offer: Which Is Better for Buyers in Today's DFW Market?
In DFW's current buyer-leaning market (2026), a strong contingent offer often outperforms a cash offer for most buyers. With 5 months of inventory, homes sitting 60-105 days on market, and sellers offering concessions, you no longer need to waive protections or tie up all your capital to win. The real advantage now goes to buyers who understand their market position and structure offers strategically — whether that's cash or financed. Here's how to evaluate both offer types in this specific market moment, with real DFW data and the financial truth behind each approach.TK Realty
Free Home Valuation & Strategic Pricing Analysis
Core Service Programs:
- Home Buying for first-time buyers, relocators, upgraders, and growing families across DFW
- Home Selling with strategic pricing, professional marketing, and full-service listing management
- Investor & Specialty Services for new construction, 1031 exchanges, luxury homes, land, and estate properties
Why Choose TK Realty:
- ✓ Trusted by customers with 113+ five-star Google reviews
- ✓ 300+ properties closed and $100M+ in sales since 2018
- ✓ Locally rooted in Roanoke — community-driven, never a corporate chain
- ✓ Core values in every transaction — Humility, Integrity, Transparency, Value
- ✓ Named Top Realtor 2023, 2024, and 2025 by Fort Worth Magazine
- ✓ Broker-owner Tyler Kreis on MetroTex and Texas Realtors Boards of Directors
- ✓ Multi-agent team handling first-time buyers, 1031 exchanges, luxury, and investor acquisitions
Understanding the DFW Market Right Now (2026)
The DFW housing market in 2025-2026 looks nothing like the frenzied seller's market of 2021-2022. Back then, homes sold in under 21 days, multiple offers were routine, and buyers routinely waived every protection just to stay competitive. That era is over — and the shift changes everything about how you should approach an offer. DFW added 177,922 residents from July 2023 to July 2024, reaching 8.3 million people — so demand hasn't disappeared. But supply has caught up. Active listings jumped 37% year-over-year, and the market is now approaching 5 months of supply, closing in on the 5-6 month threshold that defines a balanced market. Homes are taking 60 to 105 days to sell in 2026, with sold homes averaging 82 days on market in March 2026 — up from 71 days in 2025 and 63 days in 2024. In Fort Worth, homes are selling at roughly 96% of asking price. In Dallas, nearly half of sellers have cut their price at least once. Median seller price cuts reached $14,900 — or 4.1% off the initial listing price — in March 2026. Builders are actively competing with resale homes by offering rate buydowns and $10,000–$25,000 in closing cost assistance. Cash buyers represent only 12% of DFW transactions (22% in luxury Southlake), meaning 88% of deals are financed. This is the market you're operating in. It's not a buyer's market in the sense of distress or collapse — the structural demand from corporate relocations and population growth is real. But it is a market where buyers have leverage, patience is rewarded, and you don't need to sacrifice your protections to win.You're Right to Question the 'Cash Is Always Better' Narrative
For years, cash offers dominated headlines and seller preferences. But in today's DFW market with 5 months of inventory and 60-105 days on market, that dynamic has shifted. Your instinct to evaluate both options carefully is exactly right.What a Cash Offer Actually Costs You (Beyond the Purchase Price)
Let's slow this down and look at the numbers — because the true cost of a cash offer is almost never just the purchase price. The median DFW home is approximately $415,000 in 2026. An all-cash purchase means $415,000 in liquid funds leaves your accounts on closing day and gets locked into a single, illiquid asset. That capital is no longer working for you in any other way. Here's the opportunity cost most buyers skip: if that same $415,000 were invested in the S&P 500, historical average annual returns of 8-10% translate to $33,200–$41,500 per year in potential gains. That's not a guarantee — markets fluctuate — but it's a real number that deserves a place in your decision-making. On the transaction cost side, cash buyers do save on lender fees (typically 1-2% of the loan amount), appraisal fees ($500-$1,000), and loan-related title endorsements. Those savings are real. But there's a liquidity trap on the back end: if you ever want to pull equity out of a Texas homestead, the Texas Constitution Article XVI, Section 50(a)(6) limits cash-out refinancing to 80% of the home's fair market value. Your capital doesn't come back easily once it's in the walls. In today's DFW market, cash buyers can still negotiate price discounts — sellers value certainty and speed. But the premium sellers assign to cash offers has shrunk considerably compared to 2021-2022. The math needs to work for your specific situation, not just in theory.What a Contingent Offer Actually Costs You (And What It Protects)
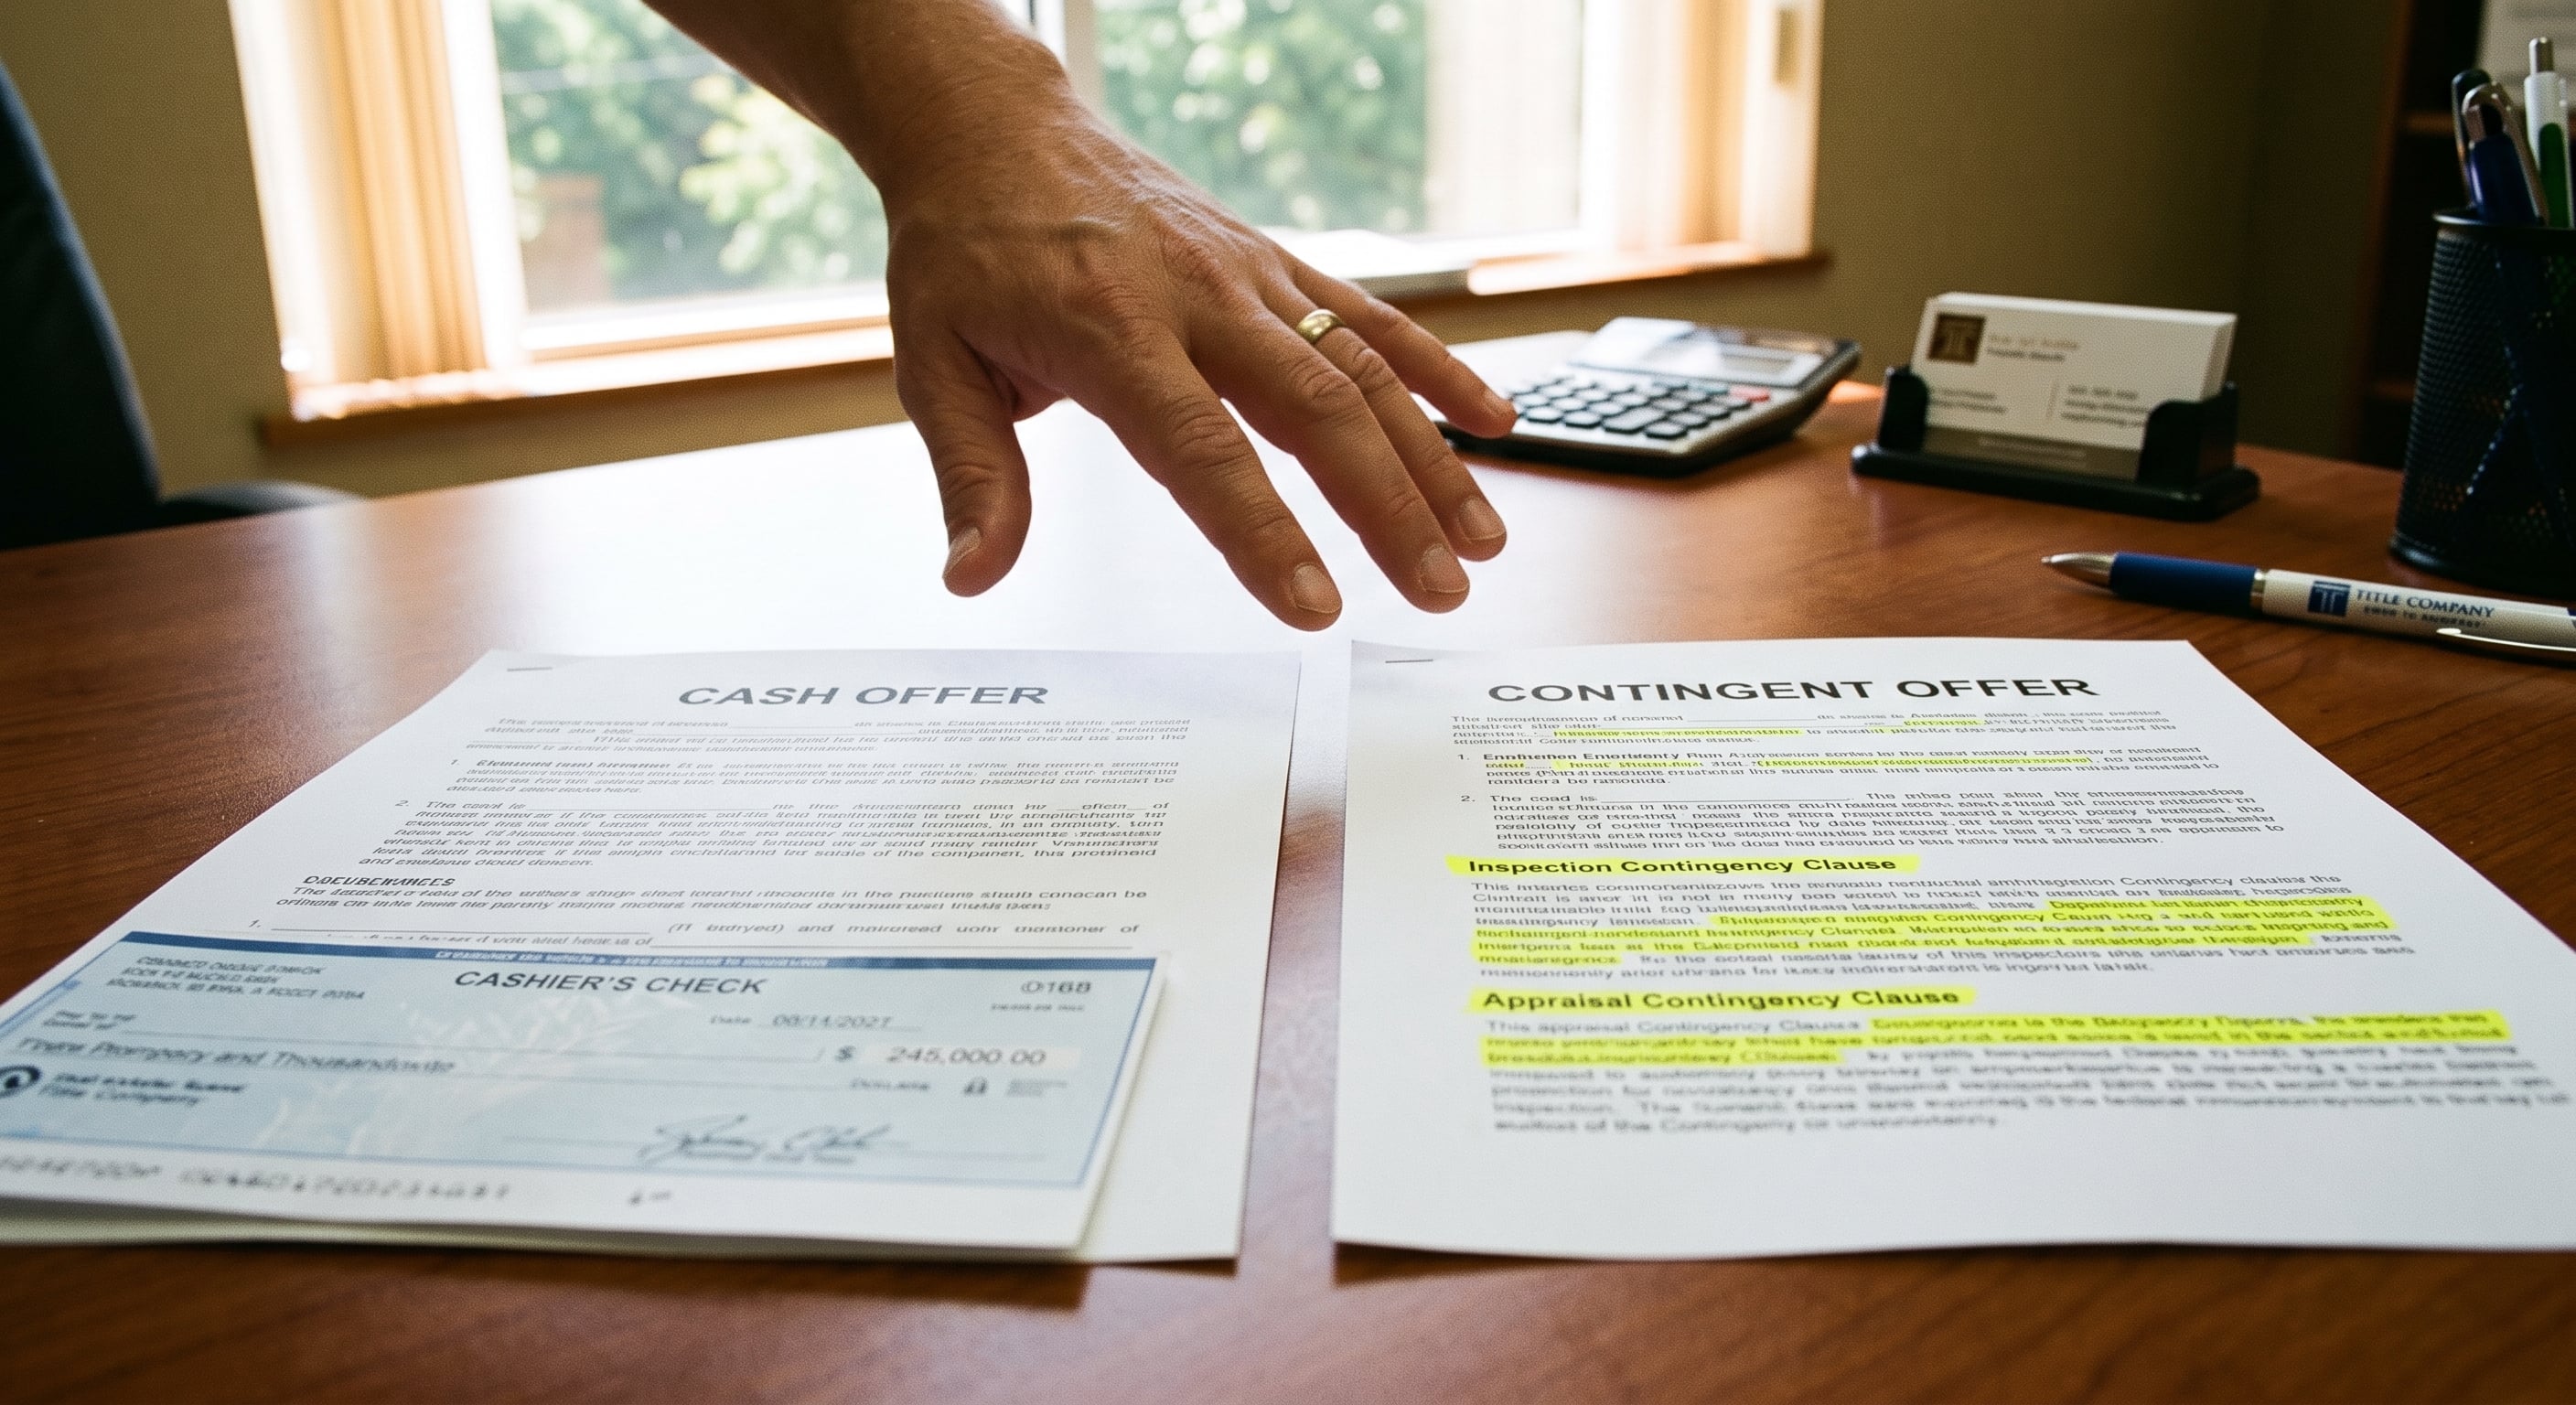
A contingent offer comes with real costs — and real protections. Understanding both is how you make a clear-eyed decision. On the cost side: 30-year fixed mortgage rates are averaging 6-7% in 2026. For a $400,000 loan at 6.5%, your monthly principal and interest payment is approximately $2,528. Add lender fees of 1-2% of the loan amount, an appraisal fee of $500-$1,000, and underwriting and processing fees, and the direct transaction costs are higher than a cash deal. That's honest. But here's what those costs buy you. A contingent offer in Texas comes with multiple legal exit ramps built into the TREC One to Four Family Residential Contract:- Financing contingency — if your loan is denied, you can exit and recover your earnest money
- Appraisal contingency — if the home appraises below the sales price, you can renegotiate or walk
- Inspection contingency — if major defects are found, you can request repairs, a credit, or termination
- Option period — typically 7-10 days in DFW, during which you can exit for any reason by paying a non-refundable option fee (usually $500-$1,500)
Head-to-Head Comparison: Cash vs Contingent in Today's DFW Market
Comparison Table: Cash vs Contingent Offers in DFW 2026
| Decision Factor | Cash Offer | Contingent Offer |
|---|---|---|
| Seller Acceptance | High (certainty/speed); premium shrinking in buyer's market | Moderate-High; more accepted now due to higher inventory and longer days on market |
| Buyer Protection | Lower — risk of overpaying without appraisal; undisclosed defects if inspection waived | High — financing, appraisal, inspection, and option period protections |
| Closing Timeline | 7-14 days | 30-45 days (conventional); 45-60+ days (FHA/VA) |
| Buyer Negotiating Power | High for price discounts due to certainty and speed | Moderate; can negotiate seller concessions, rate buydowns, closing cost credits |
| Direct Transaction Costs | Lower — no lender fees or appraisal fees | Higher — lender fees 1-2%, appraisal $500-$1,000 |
| Opportunity Cost | High — foregone investment returns on tied-up capital ($33K-$41K/yr on median DFW home) | Lower — can invest down payment difference; potential to offset mortgage interest |
| Market Fit (DFW 2026) | Still strong but less premium; best for speed, certainty, or luxury purchases | Often the smarter choice; sellers more willing to negotiate terms and concessions |
When Cash Wins (And When It Doesn't)
Cash isn't universally better or worse — it depends on your situation and the specific property. Here's where each strategy actually makes sense. Cash makes sense when: you need to close in 7-14 days due to relocation or a time-sensitive situation; the property is highly desirable or unique and still attracting competition even in this market; the seller is in a distressed situation requiring a guaranteed fast close; or you're buying in the luxury segment where cash is more common (Southlake sees 22% cash transactions, jumping to 35% for properties above $2 million). Contingent is smarter when: you want to retain capital for investments or emergencies; you need time for proper due diligence through inspection and appraisal; you want legal protection if financing falls through or the home appraises below the sales price; and — most relevant right now — the market has high inventory and long days on market, which is exactly the current DFW situation. Before committing to an all-cash strategy, verify three things: your true opportunity cost (what that capital could earn invested elsewhere), that you'll have sufficient liquid reserves after closing, and that you're not waiving inspection or title protections without fully understanding what that means. An independent market analysis or private appraisal is also worth the cost if you're skipping the lender-ordered appraisal.The Hidden Cost of Waiving Contingencies
Some cash buyers waive inspection or appraisal contingencies to "stand out." This is risky. Waiving inspection means accepting the property as-is with no recourse for unknown defects. Waiving appraisal means you could overpay significantly. In today's buyer-leaning market, you don't need to waive these protections to win.How to Strengthen Your Offer (Cash or Contingent) in This Market
The goal isn't to win at any cost — it's to win the right property on terms that protect you. Here's how to structure a competitive offer without unnecessary exposure. For contingent buyers, pre-underwriting is the single most powerful move you can make. A standard pre-approval means a lender reviewed your application and ran your credit. Full pre-underwriting means they've verified your income, assets, and credit — the only remaining condition is the property appraisal and title. This makes your contingent offer nearly as strong as cash in a seller's eyes and dramatically reduces the risk of your loan falling through. Ask your lender specifically for this before you start writing offers. Beyond pre-underwriting, consider offering a larger option fee — $1,000 or more instead of $500 — to signal commitment and compensate the seller for taking the home off the market during your inspection window. Shortening the option period from 10 days to 5-7 days reduces the seller's risk window further. And in this market, negotiating seller concessions — closing cost credits, rate buydowns — is often more effective than competing on price alone. Builders are already offering these incentives on new construction, which means resale sellers know they need to compete. For both offer types: provide bank statements dated within 30 days as proof of funds, and make sure your agent includes a strong pre-approval or pre-underwriting letter with direct lender contact information. Avoid escalation clauses unless your agent specifically recommends them — they reveal your price ceiling before you need to. If you're actively searching for the right property, TK Realty's VIP Home Search gives you access to exclusive and coming-soon listings before they hit the broader market — which matters when the right home still moves quickly.The Pre-Underwriting Advantage (Contingent Buyers)
If you're financing, ask your lender for "full pre-underwriting" — not just pre-approval. This means they've verified your income, assets, and credit; the only remaining condition is the property appraisal and title. This makes your contingent offer nearly as strong as cash in a seller's eyes, and it significantly reduces the risk of your loan falling through.Why TK Realty Is the Right Choice for DFW Homebuyers
With 113+ five-star Google reviews, 300+ closed transactions, and $100M+ in sales since 2018, TK Realty has navigated every market cycle — from the extreme seller's market of 2021-2022 to today's balanced, buyer-leaning conditions. Named Top Realtor by Fort Worth Magazine in 2023, 2024, and 2025, the team brings a track record built on honest guidance, not transaction volume. Tyler Kreis, broker-owner and locally rooted in Roanoke, serves on the MetroTex and Texas Realtors Boards of Directors — which means he's not just working in this market, he's helping shape how it operates. That regulatory depth and market intelligence flows into every client conversation. When you're deciding between a cash and contingent offer, evaluating whether to waive an inspection, or trying to understand what seller concessions are actually worth, you need someone who will slow the process down and explain the numbers clearly — not push you toward a decision that serves their timeline. Whether you're a first-time buyer navigating your first offer or an experienced buyer recalibrating your strategy for this specific market moment, TK Realty's approach is the same: clear explanations, honest advice, and a timeline built around your real life. There's no rush if it's not the right move. You can also explore the full TK Realty story to understand what sets this team apart from the typical brokerage model.Ready to make a smart offer in today's DFW market? Schedule a free consultation with TK Realty to discuss your specific situation and get a personalized strategy.
Frequently Asked Questions
Should I wait for more offers, or should I take the strong one I have now?
In the current DFW market, waiting carries real risk. Homes are averaging 82 days on market as of March 2026 — up from 71 days in 2025 — and multiple-offer situations are far less common than they were in 2021-2022. If you have a solid offer that meets your financial and timeline needs, carefully weigh the certainty of that offer against the uncertainty of receiving a better one later. A strong offer in hand is worth more than a hypothetical better offer that may never arrive, especially when carrying costs continue to accumulate each month the home sits unsold.How can I tell if a buyer's pre-approval letter is really strong, or just a basic pre-qualification?
A strong pre-approval letter means the lender has actually verified the buyer's income, assets, and credit — not just run a quick estimate. Look for language stating the buyer has been "fully underwritten" or that their financial information has been "verified." A pre-qualification is simply a preliminary estimate based on self-reported numbers and carries far less weight. Your agent should contact the buyer's loan officer directly to confirm what conditions remain, ask about the lender's confidence in closing, and verify that the letter reflects a real underwriting review rather than a soft inquiry.Is a cash offer always better than a financed offer, even if it's for less money?
Not always, but often — and the answer depends on your priorities as a seller. Cash offers eliminate appraisal and financing contingencies, which significantly reduces the risk of the deal falling through and allows for a much faster closing (7-14 days versus 30-45 days for conventional financing). In Southlake's luxury segment, 22% of purchases are all-cash, reflecting how highly sellers in premium markets value that certainty. If a financed offer is only modestly higher but carries multiple contingencies and a longer timeline, the certainty and speed of a well-priced cash offer may lead to a higher net outcome and far less stress.What happens if the top offer falls through after I've already accepted it?
If an accepted offer falls through, you typically retain the buyer's option fee — which is non-refundable — and potentially their earnest money, depending on the reason for termination and what the contract specifies. You would then relist the home or approach any backup offers you received. The practical impact is real: a failed contract means additional carrying costs (mortgage payments, taxes, utilities, insurance) and the need for fresh marketing, which can reset buyer perception of the property. This is why evaluating the strength and certainty of an offer matters just as much as its price — a slightly lower offer from a fully pre-underwritten buyer may carry less risk than a higher offer with weaker financing.What makes TK Realty different from other real estate agents in DFW?
TK Realty's approach is built on slowing the process down and explaining every step clearly — the opposite of the pressure-driven model most agents use. With 113+ five-star Google reviews, 300+ closed transactions, and $100M+ in sales since 2018, the team has earned trust by being honest about what makes sense for each client's situation, including telling clients when a deal doesn't make sense. Tyler Kreis, broker-owner locally rooted in Roanoke, serves on the MetroTex and Texas Realtors Boards of Directors, bringing deep market expertise and regulatory knowledge that most agents simply don't have. Whether you're navigating a cash vs. contingent decision, evaluating seller concessions, or just trying to understand what the numbers actually mean, TK Realty prioritizes your confidence over urgency. Schedule a free consultation with TK Realty today and get a strategy built around your real situation.Ready to Make a Smart Offer in Today's DFW Market?
Whether you're weighing cash versus contingent, trying to understand seller concessions, or just want someone to walk through the numbers with you — this decision deserves a clear conversation, not a rushed one. TK Realty helps DFW buyers move confidently, at their own pace, with honest advice and zero pressure. Schedule a Free Consultation →*Market data, property values, and trends discussed in this article are accurate as of the date of publication and subject to change. This article is for informational purposes only and does not constitute legal or financial advice. Equal Housing Opportunity. Contact us for current market conditions in your area.
Check out this article next